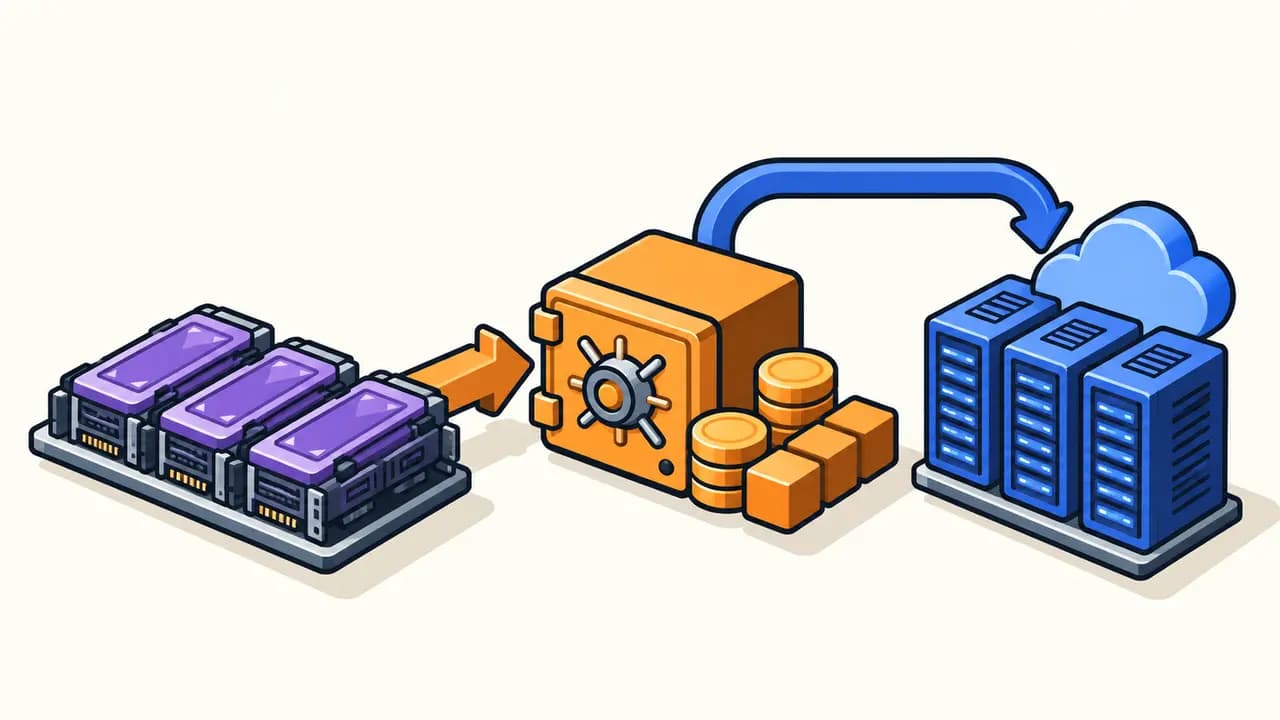
In brief: Amazon may transfer roughly $8 billion of Nvidia chips into an investor vehicle and lease them back, according to the Financial Times. Amazon and Nvidia did not confirm the potential deal to Reuters. The structure would redistribute ownership and financing risk, not reduce compute capacity.
What is being reported
The FT says Amazon recently sounded out potential investors. Thousands of Grace Blackwell chips installed across more than a dozen US data centres in five states could move into a special-purpose vehicle. The SPV would raise outside debt and lease the accelerators back. Amazon could retain up to 10% equity.
This is a report based on informed sources, not an announced transaction. The term, lease rate, guarantees and residual-value assumptions are not public. Its effect on Amazon's balance sheet and long-term obligations therefore cannot be determined.
Confirmed expansion explains the financing pressure
AWS and Nvidia announced on August 26 that they plan to deploy two million additional GPUs in 2027 and 2028, including Blackwell Ultra, Rubin and Rubin Ultra. Today's reported package instead concerns Grace Blackwell systems already bought or leased and installed in the US. The figures should not be conflated.
Amazon reported free cash flow of negative $7.6 billion for the twelve months through June, down from positive $18.2 billion a year earlier. It attributed the decline mainly to a $66.1 billion increase in net property and equipment purchases, primarily reflecting AI investment. The figures make a capital-light structure plausible but do not prove the FT report.
Pandorex Analysis: chips become financial assets
A sale-and-leaseback exchanges a large upfront purchase for contractual lease payments. For investors, the economics depend on how long the hardware earns revenue, which customer contracts support payments and how much value older accelerators retain.
That is precisely where opinions diverge. Reuters reports that banks commonly underwrite GPUs on three- to four-year depreciation schedules, while Nvidia argues that top-tier models can remain productive for up to a decade. Some lenders therefore want stronger guarantees for chip-backed financing. A large tenant with Amazon's credit quality could reduce that risk, but it cannot eliminate technical obsolescence or dependence on utilisation.
If Amazon proceeds, the larger signal would concern the financing of the AI buildout: compute chips would become separately financed assets, more like aircraft or data centres. That trend is supported by current deals, while the specific $8 billion Amazon transaction remains unconfirmed.